
Lead
Judicial scrutiny over corporate structures and aggressive tax planning has fundamentally transformed following systemic legislative interventions and apex court interpretations. The structural assimilation of tax offenses into corporate administrative liability and expanded confiscation frameworks alters the operational exposure of corporate boards, holding entities, and intermediary shell companies. Understanding this doctrinal pivot is vital for evaluating how tax crimes are investigated, prosecuted, and penalized across modern commercial jurisdictions.
The shift from viewing tax non-compliance merely as an administrative friction toward classifying it as a direct predicate for corporate criminal sanction marks an aggressive institutional doctrine. Financial gains stemming from unpaid duties, abusive corporate shields, and synthetic cross-border schemes face immediate exposure to direct and equivalent asset freezes, dismantling long-held assumptions regarding corporate insulation from criminal penalties.
Historical and Geopolitical Context
The punitive architecture surrounding tax offenses in Italy has historically oscillated between leniency and structured repression. In early post-war frameworks, custodial sentences for fiscal violations were of modest severity, compelling lawmakers to implement substantial statutory increases through Presidential Decree no. 645 of 1958, known as the Testo Unico delle imposte dirette. This enacted the first significant tightening of custodial penalties, laying the groundwork for specialized tax enforcement.
A structural watershed occurred with the historic reform embodied in Legislative Decree no. 74 of 2000, which abandoned generalized minor infractions to focus criminal sanctions on fraudulent and substantial evasive behaviors. Subsequent legislative modifications progressively consolidated this framework through to 2015, categorizing offense typologies, common statutory provisions, and specific thresholds governing attempt and consummation.
The landscape changed further with Legislative Decree no. 158 of 2015, which introduced tax confiscation in both direct and value-equivalent forms under Article 10, paragraph 1. This established asset recovery as a primary policy lever. The statutory apparatus was later augmented by Law Decree no. 124 of 2019, converted into Law no. 157 of 2019, which enacted extended confiscation (confisca allargata) and introduced tax crimes into the corporate administrative liability catalog under Legislative Decree no. 231 of 2001.
European Union integration accelerated these domestic changes through the implementation of Directive (EU) 2017/1371 on the fight against fraud to the Union’s financial interests by means of criminal law (the PIF Directive). Enacted into domestic law via Legislative Decree no. 75 of 2020 pursuant to Article 3 of its enabling act, the measure altered the legal treatment of attempted tax fraud under Legislative Decree no. 74 of 2000 for cross-border violations affecting EU value-added tax revenues.
Actors
The institutional framework governing tax criminal law involves key judicial, administrative, and regulatory bodies:
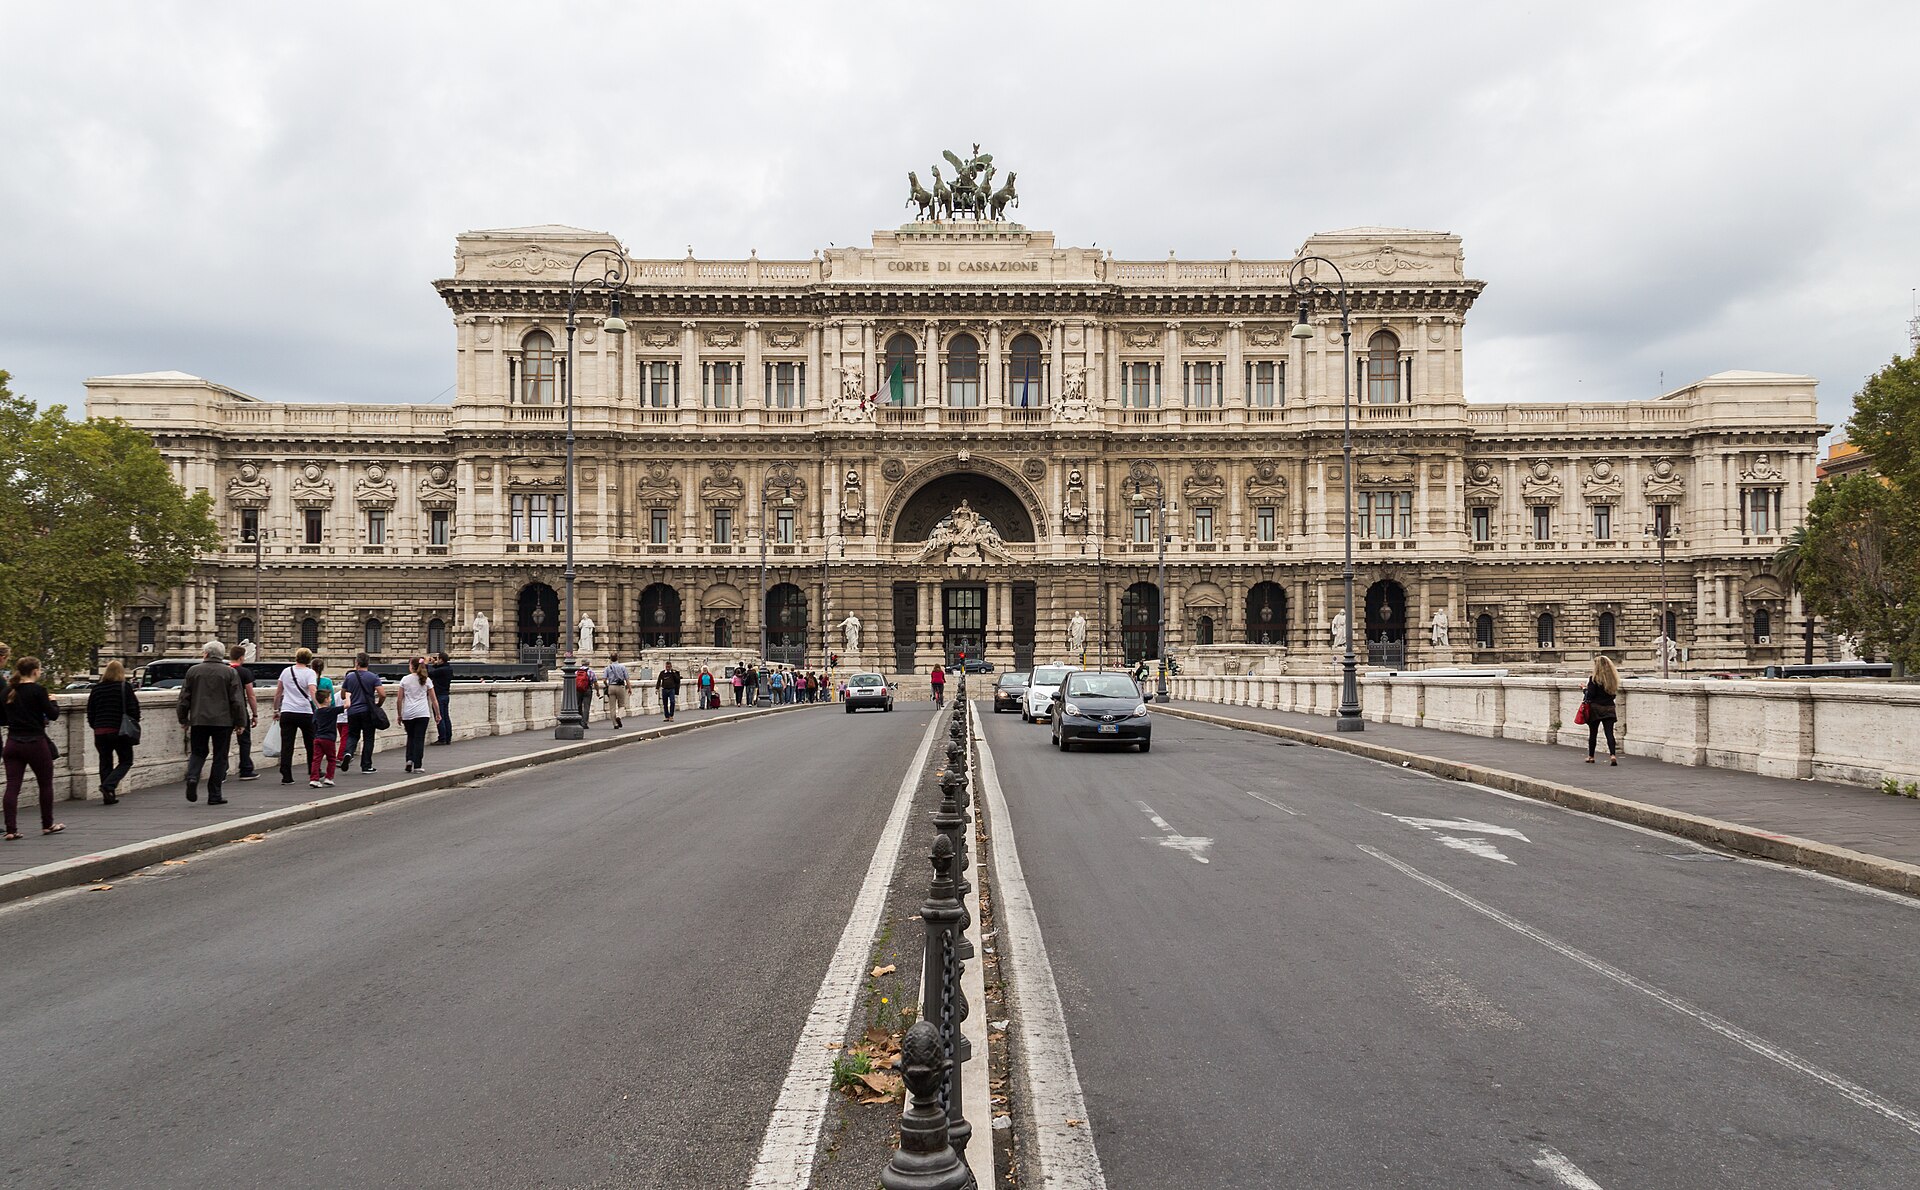
- Corte Suprema di Cassazione (Supreme Court of Cassation): The highest judicial authority in the Italian legal order. Through its Joint Civil and Criminal Divisions (Sezioni Unite) and specialized criminal benches, it establishes binding interpretations regarding asset freezes, confiscation typologies, and the conceptual definition of illicit fiscal profit.
- Guardia di Finanza: The militarized financial police corps tasked with economic crime investigations, tax audits, and asset tracing. Its operational circular dated September 1, 2020, establishes targeted enforcement methodologies regarding corporate groups and tax fraud schemes.
- Ufficio del Massimario e del Ruolo: The judicial research and analysis bureau of the Supreme Court, whose analytical report no. 3 of January 9, 2020, provided doctrinal guidance on the intersection between tax crimes, corporate liability, and asset recovery.
- Ministero della Giustizia & Ministero dell’Interno: State executive bodies responsible for legislative drafting, administrative decrees, and implementing international judicial cooperation instruments under European regulations.
- Corte Europea dei Diritti dell’Uomo (European Court of Human Rights): The supra-national judicial body whose jurisprudence governs fair trial standards, proportionality, and the substantively criminal classification of administrative penalties under the Engel criteria.
Critical Analysis of Evidence
1. The Unitary Concept of Profit and Confiscation Regimes
A primary friction in the adjudication of tax offenses lies in the legal definition of criminal profit subject to asset forfeiture. Judicial debate has focused on aligning the profit definition under Article 12-bis of Legislative Decree no. 74 of 2000 with that of Article 19 of Legislative Decree no. 231 of 2001. Doctrinal and judicial consensus establishes a unitary definition: profit represents the direct economic advantage derived from the offense, corresponding to the concrete financial saving (risparmio di spesa) that matches the unpaid tax obligation.
The profit of a tax crime must be understood as the direct economic advantage obtained from the commission of the offense, which in tax offenses coincides with the expenditure saved—namely, the evaded tax liability.
The landmark judgment of the Joint Divisions, Sezioni Unite no. 18374 of January 31, 2013 (Adami), broadened this scope specifically regarding fraudulent evasion of tax settlement under Article 11 of Legislative Decree no. 74 of 2000. In that context, profit was interpreted to include accumulated interest and administrative penalties alongside the baseline evaded principal, significantly inflating the value of assets exposed to statutory confiscation.
This framework is further refined by the distinction between direct confiscation and equivalent confiscation (confisca per equivalente), formalized in Sezioni Unite no. 29951 of May 24, 2004 (Focarelli). Direct confiscation requires a strict appurtenance link (nesso pertinenziale) between the seized asset and the criminal conduct. In contrast, value-equivalent confiscation applies to unrelated assets of identical value when the direct product or profit cannot be located.
2. Bank Accounts and the ‘Tertium Genus’ Jurisprudential Conflict
The treatment of corporate bank accounts has generated significant legal debate. In Sezioni Unite no. 19561 of January 30, 2014 (Gubert) and Sezioni Unite no. 31617 of June 26, 2015 (Lucci), the Supreme Court addressed preventive seizures under Article 321, paragraph 2 of the Code of Criminal Procedure against monetary balances held on corporate accounts.
The Gubert ruling effectively identified a specialized asset category (tertium genus) regarding monetary sums deposited in accounts belonging to the legal entity in whose interest the tax crime was committed. Because money is a fungible asset, financial deposits generated through tax savings are treated as the direct profit of the crime rather than equivalent value, allowing immediate preventive seizure directly against the corporate entity.
However, jurisdictional tensions prompted the Sixth Criminal Division of the Supreme Court to issue Referral Order no. 7021 on February 23, 2021. This order requested the Joint Divisions to clarify the operational boundaries of direct monetary confiscation, particularly concerning the necessity of tracing the precise origin of funds mixed within active commercial accounts.
3. The Doctrinal Nature of Entity Liability: Administrative vs. Substantively Criminal
The introduction of tax offenses into Legislative Decree no. 231 of 2001 via Law Decree no. 124 of 2019 revived debate regarding the true nature of corporate sanctions. While historical jurisprudence from the Joint Divisions characterized corporate liability under Decree 231 as a hybrid or ‘para-penal’ model, institutional positions—including interpretive lines from the Ministry of Justice and Ministry of the Interior—argue for its formal recognition within criminal jurisdiction.
This reclassification is driven by Regulation (EU) 2018/1805 on the mutual recognition of freezing and confiscation orders, which explicitly applies to criminal matters. Furthermore, the established jurisprudence of the European Court of Human Rights requires sanctions of high punitive severity to respect substantive criminal safeguards, irrespective of domestic formal classifications as administrative penalties.
4. Transnational Fraud, Attempt Liability, and the Anti-Abuse Paradox
The transposition of the PIF Directive through Legislative Decree no. 75 of 2020 introduced specific anomalies regarding the punishability of attempted tax evasion. Historically, domestic law under Legislative Decree no. 74 of 2000 excluded attempt liability for specific declaration-based tax offenses to prevent premature criminalization of preliminary preparatory acts. Legislative Decree no. 75 of 2020 modified this restriction under Article 3 of its enabling act, establishing attempt punishability for offenses damaging EU financial interests as defined across Articles 1 through 5 of Directive (EU) 2017/1371.
Concurrently, the interaction between criminal fraud and tax avoidance remains complex. The enactment of Article 10-bis of Law no. 212 of 2000 (the Taxpayer’s Charter) established in paragraph 13 that tax abuse and aggressive tax planning (elusione fiscale) carry no criminal relevance. While intended to establish a definitive division between legitimate financial planning, non-criminal abuse, and fraudulent evasion, judicial application continues to grapple with cases where complex corporate arrangements, holding structures, and screen companies (società schermo) border on fraudulent simulated transactions.
On subjective liability (mens rea), procedural coordination between tax and criminal jurisdictions shows notable alignment. Criminal Division Three, in judgment no. 12680 of March 19, 2020, established objective evidential indicators for proving specific intent (dolo) in tax crimes. These criteria are now routinely applied across both administrative tax litigation and criminal courts to identify fraudulent intent within complex business operations.
Transparency and Legal Basis
This dossier is compiled from official judicial proceedings, systemic studies, and statutory reports published by the Supreme Court of Cassation (Corte di Cassazione) regarding the comprehensive restructuring of Italian tax criminal law.
The primary source document is the institutional judicial report titled Riforme del diritto penale tributario, prospettive sistematiche ed esperienze applicative, presented at the seminar held in Rome on Wednesday, March 10, 2021.
Official documents and administrative acts produced by the Italian State and public administrative bodies are excluded from copyright protection pursuant to Article 5 of Italian Law no. 633 of April 22, 1941 (Legge sul diritto d’autore). They reside permanently in the public domain, guaranteeing open public access and transparency in institutional and judicial reporting.